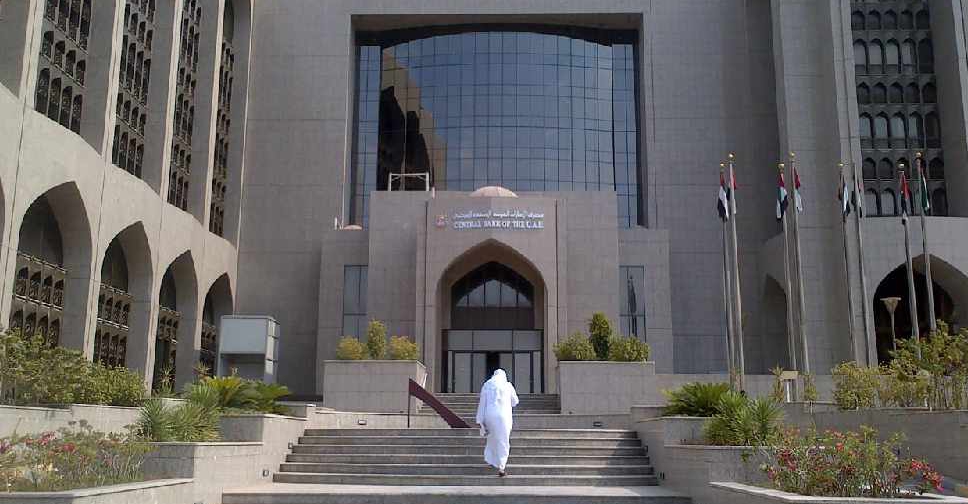
The Central Bank of the UAE (CBUAE), on Thursday, fined an unnamed exchange house AED100 million due to what it called significant failures in the company's regulatory framework.
The financial sanction is based on the results of the findings of examinations conducted by the CBUAE, with regards to Anti-Money Laundering and Combating the Financing of Terrorism and Illegal Organisations regulations.
The CBUAE, through its supervisory and regulatory mandates, endeavours to ensure that all exchange houses, their owners, and staff abide by UAE laws, regulations and standards to maintain transparency and integrity in financial transactions and safeguard the UAE financial system.

 UAE and Thailand conclude trade deal talks
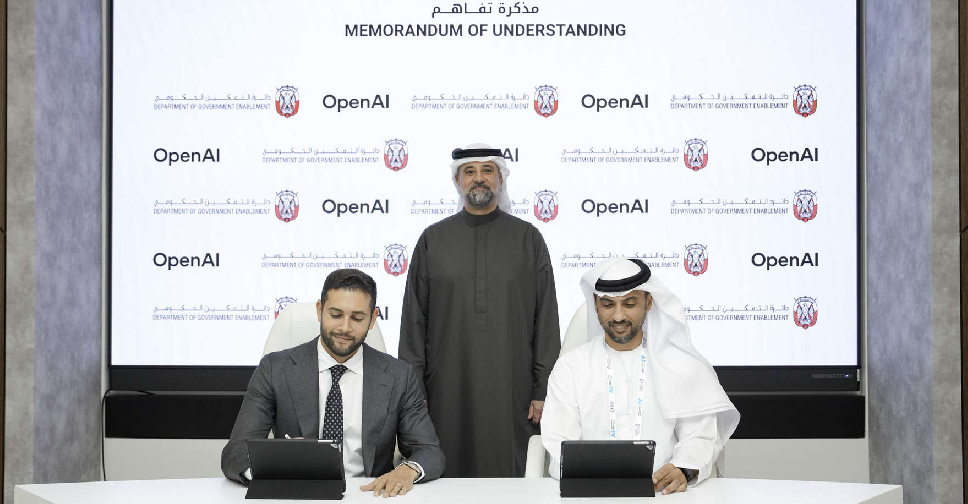 Abu Dhabi unveils major AI training programme for government and public
 IMF reaches staff deal with Pakistan, potentially unlocking $1.2 billion
 African Union launches continent's first credit rating agency
 e& reverts to Etisalat to pay homage to 50 years in business